Buying agricultural land in India involves more than agreeing on a price. State laws may limit who can purchase farmland, and a seller’s paperwork may not tell the whole story about ownership, possession or restrictions on the parcel. Tax outcomes also depend on how the land is classified and used, and on the buyer’s circumstances.
Check eligibility and the land’s records before paying an advance. Then have the proposed transaction reviewed under the laws in force where the parcel is located.
Check whether you can buy the land before paying an advance
Why eligibility rules vary by state
Land is primarily governed at the state level. Some states restrict agricultural-land purchases to agriculturists or require buyers to meet other conditions. Rules can differ on eligibility, landholding limits, permissions and how land may be used. A buyer who is eligible in one state may not meet the requirements in another.
Before committing funds, confirm the current rules with the relevant state revenue authority or a local property lawyer. Ask specifically whether you qualify, whether prior permission is needed and whether the parcel has restrictions that could prevent the proposed purchase or later use. Do not assume that a seller’s assurance or a broker’s explanation is enough.
What NRIs and OCIs should know about purchase and inheritance
Under FEMA rules, NRIs and OCI cardholders are generally restricted from directly purchasing agricultural land, farmhouses and plantation property in India. Inheritance may be permitted in circumstances where a direct purchase is not, but the answer depends on the person’s status, how the land was held and the applicable succession and FEMA rules.
If you are an NRI or OCI, get advice on both the federal rules and the state’s land laws before accepting or transferring inherited land. Citizenship, residency status and the route by which the property was acquired can matter. Do not treat inheritance as automatic permission to buy additional agricultural property.
Verify the seller, title and land records
Trace ownership and compare deeds, revenue records and mutation entries
Ask for the registered sale deed and documents showing the chain of ownership, including inheritance, partition or court documents where relevant. Compare the seller’s identity and ownership details across these papers. Check the survey or parcel numbers, area and boundaries against the relevant land and revenue records.
Review mutation entries, which record changes in the revenue records after a transfer or succession. They are useful for checking whether records have been updated, but mutation by itself does not establish legal ownership. Have a lawyer examine the underlying title documents and investigate any gaps, inconsistent names or unexplained transfers.
Also check registration and stamp-duty records, and obtain an encumbrance search for the relevant period. An encumbrance search can help identify registered transactions or charges, but it may not reveal every claim or dispute. Ask whether the land is mortgaged, subject to a lease or affected by pending litigation. Keep copies of the documents you review.
Check boundaries, possession, encumbrances, disputes and land-use restrictions
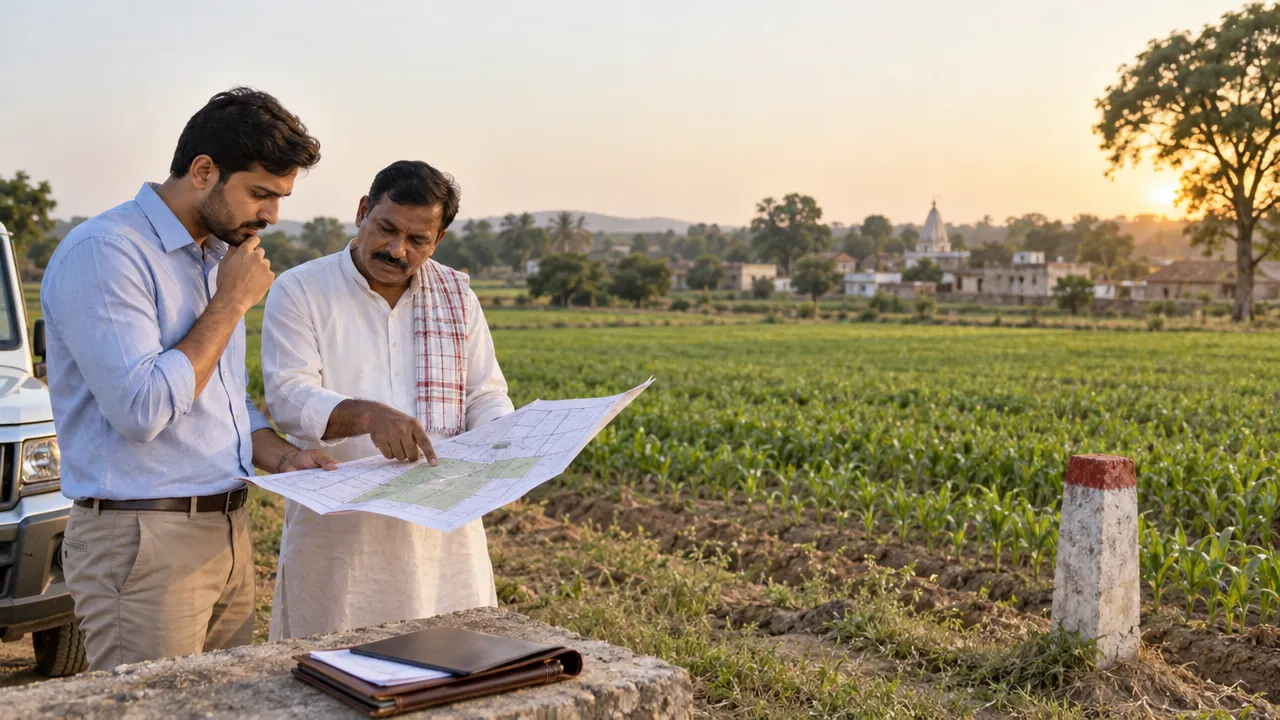
Confirm the parcel on the ground. Match its survey numbers and boundaries to official maps and records, and check who is in actual possession. Look for access to a public road, shared paths, water rights or other arrangements that may affect practical use. Where necessary, arrange a survey by a qualified professional rather than relying only on a fence or verbal description.
Check whether the land is subject to acquisition, tenancy rights, conservation rules, a ceiling limit or other restrictions. If you plan to build, develop or change its use, confirm what permissions and conversion processes apply. Agricultural classification does not automatically allow construction or non-agricultural use.
Understand the tax implications of owning and selling agricultural land
Agricultural income is not the same as income from other activities
Tax treatment depends on the source and nature of income. Income that qualifies as agricultural income under the applicable tax law may receive different treatment from earnings from unrelated activities. Owning farmland does not make other income - such as a separate business’s earnings - agricultural income. Keep clear records of the land’s use, receipts and related expenses, and ask a tax adviser how the rules apply to your circumstances.
Rural or urban classification can affect capital gains tax
The tax treatment of a sale may depend on whether the land meets the legal definition of rural agricultural land or is treated as urban agricultural land. The classification can involve the population of a nearby municipality or other local authority and the land’s distance from it. The relevant tests and how they are measured depend on the law in force for the transaction date.
Do not rely only on a village address, a revenue record or the description “agricultural land” in the deed. Have a tax professional check the applicable classification and calculate the consequences before you agree to a sale.
When Section 54B relief may apply to reinvestment
Section 54B may provide capital-gains relief when an eligible taxpayer sells qualifying agricultural land and reinvests in agricultural land, subject to statutory conditions and deadlines. Eligibility can depend on who owned and used the land, how long it was used for agriculture and when replacement land is acquired. The rules may change, including their numbering under the tax law in force for the transaction.
Treat this as a potential relief, not an automatic exemption. Ask a tax adviser to confirm the applicable provisions, timelines and documents before relying on it.
Complete the purchase with clear documents and traceable payments
Before signing, check that the sale deed correctly identifies the buyer and seller and accurately describes the parcel, consideration and agreed terms. Confirm the registration process, applicable stamp duty and any permissions required by the state. Ensure the deed reflects the actual transaction; inaccurate details can create legal and tax problems.
Pay through traceable banking channels and retain proof of payment and the source of funds. Keep the registered sale deed, title papers, revenue-record extracts, tax and registration receipts, and correspondence about the transaction. After registration, check that the relevant records are updated, while remembering that mutation is not a substitute for a valid title.
Use local legal and tax advice before closing
Agricultural-land rules are state- and parcel-specific. Before committing funds, ask a property lawyer in the state where the land is located to verify your eligibility, title and parcel-specific restrictions. Have a tax adviser review the purchase or sale under the rules in force for its date. These checks can identify issues that a price negotiation or document checklist alone will not resolve.